Friday, October 28, 2022

As a Leader, Are you Trying to Impress or Connect?


I recently listened to an interview with Jon Levin, Dean of the Stanford Graduate School of Business.  The podcast focused on communication.   Levin offered a great take on how his thinking about communciation has changed over time, as he has taken on leadership roles.  

My thinking about communication has evolved over my career. I started as a professor teaching. And when you’re giving research talks, it’s just everything is about presenting ideas and information clearly, and maybe even impressing people a little bit and getting them to change the way they think about a problem.

In a leadership role, so much more of communication is about connecting with people, establishing shared humanity, motivating them, inspiring them, sometimes challenging them. So, going through my career, that has really reinforced to me the different purposes that communication serves: to inform people, to connect with people, to motivate and inspire them.

I really love this distinction between IMPRESSING PEOPLE and CONNECTING WITH PEOPLE.   The former, of course, often involves talking AT people.  The latter means that leaders listen to others, engage them in dialogue, and collaborate WITH team members.   Every leader should think about how they build connection so as to motivate, inspire, and build commitment in their organization.  

Friday, October 21, 2022

How Leaders Can Build Trust

Source: openaccessgovernment.org

In far too many organizations, employees indicate that they do not trust senior leaders.   Why is trust so important?  It helps leaders build buy-in and commitment, particularly when they have to make difficult decisions.  It drives engagement and helps increase employee retention.   Heightened trust increases intrinsic motivation, leading to higher productivity and organizational effectiveness.

How can leaders build trust?  Here are five strategies that prove quite effective:

  1. Be transparent.  That doesn't just mean providing more information about the performance of the organization.  It means helping others understand how you think.  What are the criteria you use to make big decisions?  What is the rationale for particular actions?  What are the values guiding your behavior?
  2. Walk the walk.  If you articulate a certain set of values and norms, then be sure that you are acting in ways consistent with those principles.  Root out any instances of misalignment between words and actions. 
  3. Lead fairer decision-making processes.  Fair process doesn't mean giving people their way. It means giving people voice and genuinely considering their views before making key decisions.  As noted leadership scholar Michael Watkins says, it means avoiding the "charade of consultation." By that, he means not asking for input AFTER you have already made up your mind.  Employees see right through the charade when you ask for advice, yet simply act in the way you always intended from the start. 
  4. Own your mistakes. If you fail, acknowledge it.  Explain what happened and why, and be clear about how you plan to fix the problem. Don't throw others under the bus.  Instead, describe what you learned from the failure. 
  5. Listen early, often, and actively.  When you speak to large groups of employees, make sure that at least half the time is reserved for questions.  Don't force people to submit questions in advance.  Be willing to show some vulnerability and address questions in the moment.  If you don't know the answer, say so.  Tell people how and when you will get them the answer.  

Wednesday, October 19, 2022

Case Companion: A New Tool from Harvard Business Publishing


In the past few months, Harvard Business Publishing has begun distributing a new online tool that I developed with a terrific team from Torrance Learning and HBP.  

The tool - Case Companion - helps students learn how to analyze a case study.   To date, we have received some very positive feedback from students and faculty.  We look forward to using this tool to help our students improve their performance in case-based classes.  

CFOs, Leadership Development, and the Cost of Losing Talent

Source: Forbes.com

Michael Pickrum has written a good article for CFO magazine titled, "The CFO's Role in Leadership Development."   He argues that talent is crucial to achieving an organization's strategic and financial goals, and that the job of leadership development does not rest only with the chief human resource officer.  The CFO can and should play a vital role.  Among other things, Pickrum argues that the CFO can help the organization recognize the value of leadership development efforts.  He writes,

Use data and more holistic analysis to aid better decision-making. What are the costs for contracting or recruiting externally versus upskilling internal high performers? Apply your visionary eye to this analysis. What are those costs over the long-term, given the value of in-house knowledge and retaining those who possess both the expertise and the experience with your organization’s way of working?

In short, Pickrum makes the case that CFOs can help organizations identify and quantify the costs and risks of losing key talent.  What precisely is the damage done by high employee turnover?  What benefits will we acheive if our development efforts improve the retention of highly talented employees?  Many CFOs (and other top executives) question the ROI of leadership development efforts.   Yet, CFOs should do more than ask the question in a theoretical way.  They should help the organization develop an accurate and thorough understanding of the potential benefits of leadership development efforts as well as the risks and costs of NOT investing in leadership development.   The connection between development and retention is crucial, and understanding the true cost of employee turnover is essential.  

Thursday, October 13, 2022

Flaws in the Rationale for the Direct-to-Consumer Business Model


Alexandra Sternlicht has written an article this week for Fortune titled "How Silicon Valley’s retail revolution withered. Eight years after Allbirds and Glossier were born, VC investors say direct-to-consumer is dead."  She quotes several investors, including Nicole Johnson, a partner at venture capital firm Forerunner.  

“We’re a whole decade past where pursuing the DTC model was at the forefront of innovation and retail, or was interesting on its own,” Johnson says. A direct-to-consumer sales channel is just “table stakes” today, she says—a useful feature for a young consumer brand, but not a business model in its own right.

It’s a sentiment echoed by numerous VC investors that Fortune spoke to, reflecting significant changes that have altered the internet landscape, as well as the shifting mindset among private company investors at a time of economic uncertainty. If direct-to-consumer startups were once touted as the harbingers of a retail revolution, today they are viewed by VCs as relics of a different era.

I found the article quite thought-provoking, but I'm particularly interested in reflecting on the rationale that many executives and entrepreneurs use to support a DTC business model.   Often, you will hear people say that the DTC model enables the startup to "capture the margin" otherwise obtained by the brick-and-mortar or e-commerce retailer.  Of course, that thinking is DEEPLY flawed.   Yes, you aren't giving away the "mark-up" to the retailer.  However, you ARE spending a considerable amount of money on your own marketing to build brand awareness, since you don't have the assistance of the retailer.  You have to find a way to distribute the product, and that "last mile" to the consumer's home can be quite expensive.  Moreover, if you end up opening some of your own brick-and-mortar stores, as some of these startups have done, then you are investing heavily in assets and will have to generate sufficient additional profit to maintain a healthy return on those expensive assets.  In short, the retailer does serve a very useful function for a nascent brand.  This is not to say that I believe DTC business models are not viable.  I'm simply arguing that entrepreneurs should not fool themselves into thinking there's easy money to capture by cutting out the retailer.   

Friday, September 30, 2022

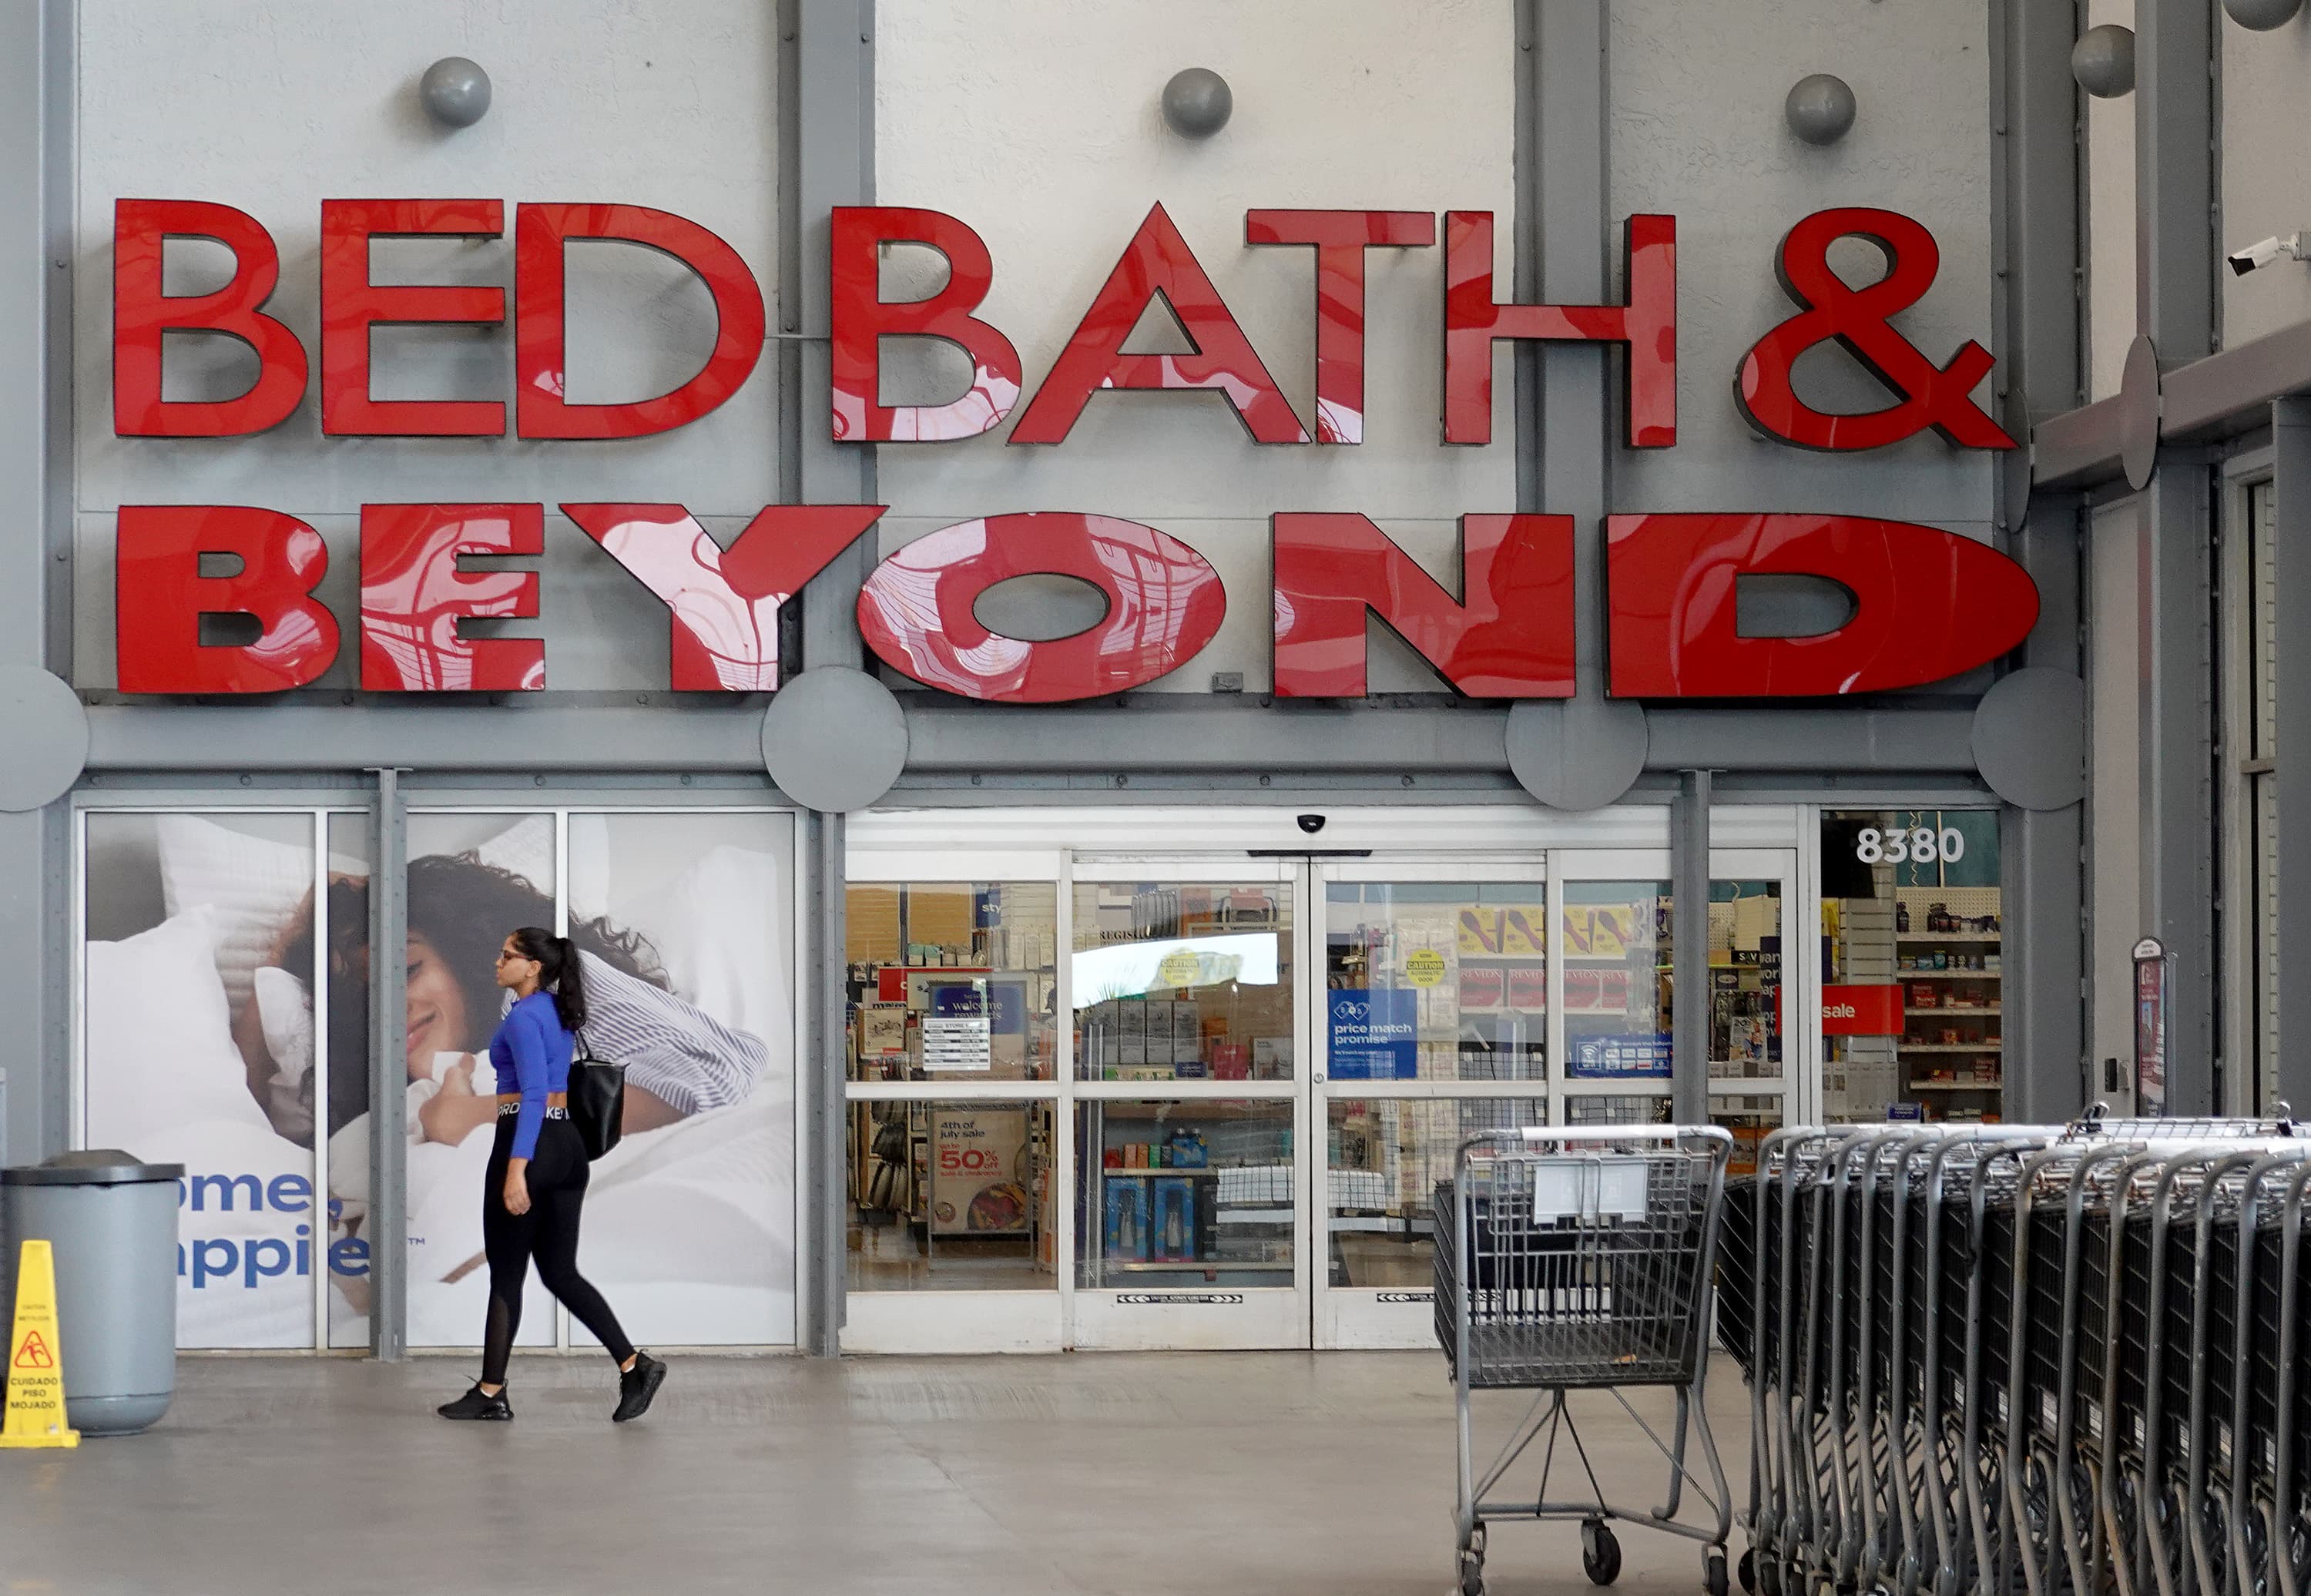
Why Does Our Firm Exist? Lesson from the Collapse of Bed, Bath, and Beyond

Source: CNBC

Phil Wahba has written a detailed and highly informative account of the collapse of Bed Bath and Beyond for Fortune.  He points out that the retailer will generate about half as much revenue this year as they did just four years ago.  Tragically, CFO Gustavo Arnal took his own life earlier this month, in part due to the stress of the situation at the retailer.

Wahba chronicles the many reasons for the declining revenue and huge losses at the retailer.  They include executive turnover, supply chain systems failures and deficiencies, and a poorly designed effort to promote new store brands while reducing the reliance on coupons and discounts.   

Wahba closes the article by writing, "During the August investor presentation, a Baird analyst said to Gove (interim CEO): 'Just trying to understand how you really differentiate the business by selling product that is widely available at other retailers.' That is exactly what Gove has to figure out, and fast."

At another point in the article, Wahba writes, "Bed Bath & Beyond has to figure out why it needs to exist in consumers’ eyes."  Indeed, that is the ultimate question for any company.  Why do we exist? What value do we bring to the table for our customers that others cannot provide?  If you can't answer that question, you don't have a viable strategy at all.   Every CEO should be asking themselves that question, but especially if you are leading a brick-and-mortar retailer these days. 

Monday, September 26, 2022

How Important Are Face-to-Face Interactions for Innovation?

Source: www.lifesize.com

Much has been written about the impact of remote work on collaboration and innovation in the workplace. Yet, few rigorous studies have attempted to document the actual impact on innovation. Now comes a fascinating new paper from David Atkin, M. Keith Chen & Anton Popov.  They used an enormous amount of smartphone geolocation data to track face-to-face interactions.   Their research sample includes over 51,000 employees in Silicon Valley in 2016 and 2017 (pre-pandemic).   Here's an excerpt from their paper:

Our rich data on interactions allow us to open the black box of knowledge spillovers and isolate a particular channel: face-to-face meetings. To do so, we first link worker interactions—measured by the probability that a worker from one establishment “meets” a worker of another establishment by being in the same place at the same time with patent citations between their employers, an observable proxy for knowledge flows. 

To calculate these meeting probabilities, we combine smartphone geolocation data with maps of building rooftops for all patenting firms in Silicon Valley, assigning workers to establishments based on where they spend a large fraction of their waking hours. To assign firm-level citations to establishments, we scrape citation data from recent patent applications and use the inventors’ hometowns coupled with the housing locations of workers to probabilistically assign citations across multi-establishment firms. The resulting dataset of establishment-to-establishment worker meetings and citations reveals a strong positive relationship between face-to-face interactions and knowledge flows, even after conditioning on rich controls for the physical distance between establishments.

Note the final sentence.  Face-to-face interactions enhanced knowledge flows. They documented a strong positive effect of face-to-face interactions on patent citations.  Here's more from the authors:

Implementing this approach, we find that face-to-face meetings significantly increase citations between establishments, with the strength of the effect twice the impact of physical distance on citations. Eliminating a quarter of face-to-face meetings in Silicon Valley would reduce the number of citations by approximately 8 percent..." 

Naturally, some will argue that we have learned how to collaborate remotely during the pandemic, and have we have mastered a batch of technologies that promote virtual collaboration.   Certainly, we have  become much more effective at communicating and collaborating with others spread across remote geographic locations.  Yet, remember that this study documents many informal, serendipitous face-to-face interactions among employees.   Those interactions are much harder to replicate virtually.   While many leaders are concerned about losing employees if they try to mandate a return to the office, they do have to consider this study's implications regarding remote work and innovation.  Hopefully, more researech will follow, enabling us to gain a deeper understanding of the value of face-to-face interaction in the new product and new process development process. 

Wednesday, September 21, 2022

How Employees Perceive Those Who Undercommunicate vs. Overcommunicate


Some leaders communicate early, often, and quite effectively.   Others overshare.  They send out a constant stream of messages, perhaps risking information overload for their organization members.  Finally, perhaps most often, we find that leaders undercommunicate.  They fail to offer transparency, and they fail to keep employees abreast of the latest developments at the firm.   Scholars Francis Flynn and Chelsea Lide conducted a great new study to examine the perceptions of employees in the cases of overcommunication vs. undercommunication.   They found that employees clearly prefer more communication to less, even if the risk of information overload exists.   Unsurprisingly, the scholars find that most leaders believe that they are communicating sufficiently, when in fact, they are not.  Here's more on the specific perceptions employees have and their implications for leaders, from Stanford Leadership Insights: 

Flynn and Lide’s research shows that employees’ preference for too many versus too few messages stems from the perception that even if an overcommunicating leader can’t communicate the ideal amount, at least they mean well. Overcommunicators “may be given the benefit of the doubt by their employees, who might view them as trying to meet their needs, even if they are not necessarily succeeding,” Lide says. Making an effort can give the impression of empathy, whereas undercommunicators are “not really seen as trying at all. Instead, they tend to be seen as really missing the mark in terms of meeting the needs of their employees.”

Flynn says that these results contrast with prior research that found that information overload hurts employee performance. “Overcommunication may be seen as annoying and a nuisance, but it’s not seen as a damning flaw for a leader, partly because a leader’s overcommunication is seen as an attempt to benefit you, even if it is misguided, as opposed to an attempt to undermine you or simply ignore you.”

Friday, September 02, 2022

Failing to Prepare for a CEO Succession

Source:  CNBC


Yesterday, Starbucks announced the hiring of a new CEO -  Laxman Narasimhan.  His former organization's stock (Reckitt Benckiser) dropped by 5% upon release of the news, suggesting investors believe its a significant loss for that firm.

As most readers know, former CEO Howard Schultz had to step in as interim leader of Starbucks several months ago, after the departure of Kevin Johnson.   The move represented Schultz's second return to the firm after his long tenure as CEO. On two occasions, Schultz had to step in when the firm was underperforming, and in both cases, it appeared that Starbucks did not have a successor ready to take over.  Why was Starbucks not prepared for these two transitions?  Moreover, given the problems Schultz has unearthed and encountered during his few months as interim CEO, one wonders if the Board didn't act quickly enough to move on from Kevin Johnson.  

These changes at Starbucks came to mind when I thought about a recent paper published by qresearchers David Larcker, Brian Tayan, and Edward Watts. They found that, "many companies are slow to terminate underperforming bosses, get caught flat-footed when a CEO suddenly departs, and often fail to appoint a viable or permanent successor."  Here's an excerpt from the Stanford Insights article profiling this research:

Succession planning is a taboo subject that tends to be neglected in many companies, Larcker says. One reason is that directors may feel awkward about broaching the subject with CEOs, as it suggests dissatisfaction with their performance. “It’s like coming home from school with a bad report card and explaining it to your parents,” Larcker says. “It’s not a fun thing to do.” And personal ties can make directors go easier on the CEO.

One of the most striking findings unearthed by the paper was that 4 out of 10 CEOs retain their jobs despite five years of worst-in-class performance based on return on assets.  Larcker puts this down to risk aversion. A CEO search can be time-consuming and expensive, and the stakes are high. One study estimates the cost of appointing the wrong leader at more than $100 billion. Bad picks can cause stock price drops along with stalled momentum, lost customer goodwill, and diminished trust within the organization. “There’s a reluctance to do it,” Larcker says.

Friday, August 26, 2022

The "Quiet Quitting" Debate

Source: The Street

Several weeks ago, Lindsay Ellis and Angela Wang wrote an article for the Wall Street Journal on the "quiet quitting" phenomenon in the workplace.   Here's an excerpt:

Zaid Khan, a 24-year-old engineer in New York, posted a quiet quitting video that has racked up three million views in two weeks. In his viral TikTok, Mr. Khan explained the concept this way: “You’re quitting the idea of going above and beyond. You’re no longer subscribing to the hustle-culture mentality that work has to be your life,” he said. Mr. Khan says he and many of his peers reject the idea that productivity trumps all; they don’t see the payoff.

Naturally, the concept of quiet quitting has sparked a ferocious debate about work ethic, employee engagement, and organizational culture. Today, Kathryn Dill and Angela Wang wrote an article for the Wall Street Journal about the "backlash" against the quiet quitting movement. They present several people pushing back:
  • Arianna Huffington: “Quiet quitting isn’t just about quitting on a job, it’s a step toward quitting on life."
  • Kevin O'Leary: “You have to go beyond because you want to. That’s how you achieve success."
  • Amy Mosher: “It’s not about the quiet quitters. It’s about everybody else and the unfairness that occurs there."
For me, the discussion certainly creates a fair amount of concern.  I do worry about work ethic among a segment of the workforce.  I'm someone who loves my work and has always tried to go above and beyond for my students and my institution.  I would have a very hard time even contemplating quiet quitting.  However, I do understand why some employees have disengaged.  Moreover, I think the quiet quitting phenomenon should cause business leaders to seriously rethink four key issues.  They have to address these organizational weaknesses if they want to prevent people from disengaging in this manner:
  1.  Why are people disengaged? Is it really because they are overworked and trying to dial back their workload, or is it because you have not provided them meaningful, purposeful work and some voice in the organization?  Would they work much harder if they were passionate about a project or believed that their work could have a substantial impact on customers and other constituents of the organization?  The job here is to rethink the roles people have and the way that work gets done.  
  2. How are we measuring performance and providing feedback?  Is it possible for someone to coast unnoticed?  If so, that's deeply problematic.  Managers need to have a firm grasp on the way that work gets done, as well as how the workload is shared (equally or unequally) among their team members.  Providing feedback often is critical, but so is listening to hear people's concerns about their role and the organization's processes and systems.  
  3. Are we investing appropriately in developing our people?  How can we improve their skills and capabilities?  Workers will invest in their organizations if the leaders demonstrate a willingness to invest in them.  Yes, you might invest in their training and development and then they might leave.  The investment is worth the risk.   They will disengage or perhaps leave anyway if they are not growing and developing on the job.  
  4. Have our highest performers developed a perception of unfairness about how the workload is shared?   Perceptions of fairness have a substantial impact on organizational commitment and buy-in.  You will lose your best people if they think others are not carrying their fair share of the workload.  

Monday, August 22, 2022

Becoming Vigilant & Detecting Early Warning Signs

Source: Flaticon

Wharton decision-making experts George Day and Paul Schoemaker have identified four strategies for becoming vigilant leaders who can detect early warning signs effectively.  They recognize that the best companies overcome tunnel vision, avoid complacency, and scan the environment successfully to identify opportunities and threats.  Here are their four strategies:

1. Assemble a diverse team of independent thinkers: "One way to scope is by assembling a diverse team of independent thinkers from both inside and outside the company who can, as one of our clients phrased it, 'tap into the organization’s paranoia' and invite everyone to voice hunches, concerns, doubts, or intuitions that would otherwise remain dormant."

2.  Ask questions that acknowledge the limits of existing knowledge:  Effective leaders admit what they personally don't know and where key gaps exist in the organization's expertise.  Day and Schoemaker advocate asking three types of questions: learning from the past, interrogating the present, and anticipating the future.  They write, 

One method for learning from the past is to use past successes to create watching and listening outposts in other markets by asking, “Who there has a consistent record of seeing sooner and acting faster?” and “What is their secret?” Many companies interrogate the present by monitoring blogs, social media sites, and chat rooms for signs of brewing trouble with customers, with an eye toward timely remedial action. Vigilant organizations pay special attention to customers’ evolving behaviors and needs. One way to do this is by studying “edge cases” that could suggest opportunities or threats. (In engineering, the term edge is used to describe situations that purposefully push the limits.) To prepare for what’s ahead, leaders can develop different scenarios that reflect how today’s uncertainties might play out in years to come. To stimulate scenario planning, leaders should pose guiding questions about the future such as “What surprises could really hurt us (or help us)?” and “What might be some future surprises as big as those that we saw in recent decades?”

3.  Use active environmental scanning techniques:  By that, the scholars mean that you should develop hypotheses and then use scanning to try to test those hypotheses.

4.  Employ the wisdom of crowds to choose which signals to amplify and clarify:  Scanning can identify many opportunities and threats.  The challenge, then, is to determine which issues on which to focus attention more closely.  One way to choose is to employ the wisdom of crowds - let a broader group of people voice their opinions as to which issues warrant further scrutiny. 

Wednesday, August 17, 2022

Should Disney Divest ESPN?

Dan Loeb, (Source: CNBC)

News reports this week indicate that activist investor Dan Loeb has written a letter to Disney's leadership team, calling on the firm to make a series of strategic changes. Specifically, Loeb recommended a divestiture of ESPN. He also recommended that Disney accelerate the planned acquisition of Comcast's 33% stake in Hulu, and then for Disney to integrate Hulu into its Disney+ streaming service.  Disney's leadership has rebuffed Loeb's attempts to push for change.  

The ESPN recommendation certainly has triggered a lively debate.  Students will find this question an interesting one that goes directly to the heart of many core corporate strategy concepts. On the one hand, ESPN has been a cash cow for Disney for years. According to CNBC, "Disney is making more money from cable subscribers than any other company solely because of ESPN. ESPN and sister network ESPN2 charge nearly $10 per month combined, while Disney requires pay TV providers to include ESPN as part of their most popular cable packages."  Moreover, ESPN+ has become an important part of Disney's efforts to offering streaming options for customers.  ESPN+ has had limited content to date, but perhaps, Disney will eventually offer customers an opportunity to stream all Disney and ESPN content in a true over-the-top option for those wishing to cut the cord.   

Imagine having all Disney cable channel content, all ESPN cable channel content, and all Disney/Hulu streaming content available directly to customers who don't want to purchase cable.  Disney has been reluctant to make this type of aggressive move, in part because the firm continues to generate a ton of cash from fees secured through cable TV subscriptions.  Moreover, Disney would anger cable television partners greatly if it circumvented them completely and went directly to customers.  Still, as more and more people cut the cord, the calculus there may change, and Disney may pursue a complete over-the-top solution for customers.  

On the other hand, in corporate strategy, we typically argue that multiple businesses should only be owned and operated under one roof if they pass two tests:  the better-off test and the ownership test.  The better-off test asks whether significant economies of scope exist, such that ESPN has a stronger competitive advantage because it is owned by Disney.   Loeb argues that it is not obvious ESPN has a more powerful advantage because it is part of the Disney corporate family.  For example, in his letter, he writes, "“ESPN would have greater flexibility to pursue business initiatives that may be more difficult as part of Disney, such as sports betting."  Moreover, the synergies between ESPN and other parts of Disney do exist, but they are not nearly as substantial as, for example, the synergies between the theme parks and the movie studio.  

The ownership test asks whether the corporate parent needs to own a particular subsidiary to actually achieve key benefits of collaboration.  Could another organizational arrangement (ranging from market contracts through strategic alliances or joint ventures) be more efficient and effective than full ownership?  Here too Loeb argues that ESPN may not pass the ownership test.  He writes, "We believe that most arrangements between the two companies can be replicated contractually, in the way eBay spun PayPal while continuing to utilize the product to process payments.”  In other words, ESPN could still work with Disney and its portfolio of companies without being fully owned by the corporate parent.   This argument reminds me of one criticism back when Disney purchased ABC in the mid-1990s.  Some analysts pointed out that Disney already collaborated closely with ABC on events such as the Disney Sunday night movie of the week on ABC (which Michael Eisner would introduce).  The analysts then argued that Disney could pursue more of those types of partnerships and collaborations without having to spend billions to acquire ABC. 

The debate will be fascinating to watch.  The key point here is that Disney should not necessarily own ESPN simply because the subsidiary is profitable.  It also should not necessarily divest ESPN simply because cord-cutting is reducing subscribers at the sports network.  The longer strategic view should be driving this decision with a focus on these two critical corporate strategy tests.  


Tuesday, August 09, 2022

Rationalizing a Splurge: Not Just An Individual Decision-Making Error

Source: Tripadvisor

University of Chicago Professor Abigail Sussman has conducted some interesting research on how and why individuals tend to rationalize splurging.  She has studied this behavior in both the context of financial decisions and eating/dieting behavior.  Sussman finds that people tend to view decisions in isolation, and they view a particular consumption decision as a special one-time event.  Oh, it's a wedding, and it's a special celebration... so I can splurge on the giant piece of wedding cake.  Or, I have an event to attend, so it's ok to splurge on a nice new suit.  Examining events in isolation, as one-time events, enables us to deviate from disciplined decision making.  

People don't tend to look at categories of decisions.  For instance, there most likely are a series of opportunities to splurge on various delicious food and spoil our diet.  The wedding cake is not likely the only chance to splurge.  We have to stop looking at decisions in isolation, according to Sussman. 

The same logic holds for business decisions, in my view.  Company leaders sometimes can perceive opportunities or threats as one-time special events, and thereby justify an investment that might otherwise seem inadvisable.  For example, executives might convince themselves that this acquisition opportunity is unique, and that they simply can't let it pass them by.   They have to overpay, or they will never have a similar chance in the future.  Of course, the opportunity often is not that unique, and overpaying often leads to disaster.  Exercising some discipline and restraint is essential in these situations.  Ask yourself: Is this situation as unique as we are portraying it?

Wednesday, August 03, 2022

Not-so-Hidden Costs of Employee Turnover

Source:  Workstyle 

We all know that employee turnover can be very expensive.  Searching for, hiring, onboarding, and training new employees proves to be a costly endeavor for most firms.  If turnover increases, these costs can become quite burdensome.  A new study documents another significant cost of employee turnover - the decrease in product quality that can result from that loss of experienced and knowledgeable employees.  The paper is titled, "The Hidden Cost of Worker Turnover: Attributing Product Reliability to the Turnover of Factory Workers" by Ken Moon, Prashant Loyalka, Patrick Bergemann, and Joshua Cohen.  

The scholars studied the failure rates of 50 million cellphones produced by a major Chinese manufacturer and tracked the performance of those phones over four years of customer use.   Here's an excerpt from Knowledge@Wharton documenting the findings: 

  • Each percentage-point increase in the weekly turnover rate for workers increased product failure by 0.74% to 0.79%.
  • Failure was 10.2% more common for devices produced in the high-turnover weeks following payday, which was once a month, than for devices produced during the lowest-turnover weeks immediately before payday.
  • In other weeks, the assembly lines experiencing higher turnover produced an estimated 2% to 3% more field failures on average.
  • The associated costs amounted to hundreds of millions of dollars.

Thursday, July 28, 2022

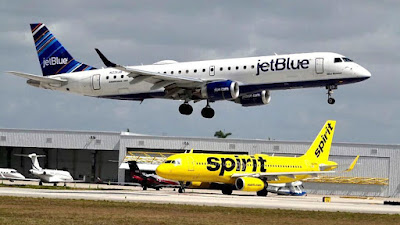
JetBlue Acquires Spirit Airlines: Will Straddling Work?

Source: Getty Images

The bidding war for Spirit Airlines has ended.  JetBlue and Frontier both sought to acquire Spirit.  Today, we learn that JetBlue has completed the deal at a price of $3.8 billion.  Alison Sider of the Wall Street Journal reported on the deal, quoting JetBlue CEO Robin Hayes: 

Buying Spirit would supercharge JetBlue’s growth, accelerating its plans by years, Mr. Hayes has said. The combined airline will have 458 planes—up from JetBlue’s fleet of just over 280 jets now—and will have over 300 more on order. Spirit’s pilots are a big part of the allure as well, at a time when airlines are struggling to replace the thousands who retired during the pandemic and are facing a growing shortfall.

Will the deal create value in the long term for JetBlue?  It's a fascinating question.  Historically, firms in the airline industry has struggled to be consistently profitable.  Richard Branson once joked that the easiest way to become a millionaire is to start as a billionaire and then open an airline.  Airlines have had even more trouble being profitable when they have tried to straddle two contrasting business models.  For instance, when Delta launched Song to compete with the likes of Southwest, they struggled mightily.  The same goes for United with Ted, and British Airways with its Go! subsidiary - which aimed to compete with EasyJet and Ryanair in Europe.  In each case, the full-service legacy carrier tried to also run a low-cost subsidiary, and the two business models did not co-exist successfully in the same corporation.  

 
"The offer of $3.6 billion, or $33 per share, represented a premium of around 30% over the price Frontier had agreed. Clearly, JetBlue sees a value in the carrier, but why?  On the surface, they aren’t exactly a match made in heaven. Spirit is a true ULCC (ultra low cost carrier), lightweight, efficient and no-frills; JetBlue is very much a hybrid airline, offering better services at affordable price points, but not truly low-cost. At first glance, Frontier looks to be the better option, but how does that pan out when we consider routes, fleet, and what’s best for the passengers?"  

Bailey concludes that Frontier seemed a better fit as you consider competitive positioning, fleet configuration, and route network.  She explained, "The Frontier-Spirit tie-up would have created the largest ULCC in the country, with a fleet of almost 500 aircraft targeted by 2026."  

Perhaps, though, JetBlue doesn't plan on operating two contrasting business models moving forward.  A quote from CEO Robin Hayes in the Wall Street Journal today seems to suggest a shift away from the ULCC strategy at Spirit:

“This is about creating a larger JetBlue,” Mr. Hayes said Thursday. JetBlue has said it plans to retrofit Spirit’s distinctive bright yellow planes to match its own fleet, including tearing seats out of Spirit’s more crowded cabins. The combined airline would be based in New York, with Mr. Hayes at the helm, the airlines said Thursday.

Ok, so perhaps we won't see an attempt to straddle.  This quote though suggests a different question: If JetBlue plans on transforming Spirit to match the existing JetBlue strategic positioning, then what's the rationale for the merger?  Why acquire the airline rather than just contining to add planes and routes to the existing JetBlue network?  It will be interesting to hear and see why acquisition might create more value than organic growth in this case.  Many people have their doubts about this deal... understandably.  

Monday, July 25, 2022

Rules for Living a Happy Life

Image source: Forbes

Harvard Business School Professor Arthur Brooks writes a terrific column for The Atlantic about achieving happiness in life. He also teaches a course on this subject to MBA students, as described in this recent Wall Street Journal article. To celebrate his 100th column this weekend, Brooks highlighted his "three biggest happiness rules."

Maxim 1: Mother Nature doesn’t care if you are happy.

Brooks argues that we are wired to desire and pursue worldly rewards such as power and wealth. However, these materialist pursuits rarely lead to enduring happiness.

Maxim 2: Lasting happiness comes from habits, not hacks.

Books, social media, and television all love to proclaim the value of various "hacks" for increasing our happiness.  While these may provide a short-term boost for us, they also don't tend to lead to substantial and enduring increases in our happiness.  Instead, Brooks argues we should focus on cultivating good habits, rather than chasing the latest popular hacks.  

Maxim 3:  Happiness is love.

Brooks writes, "Research on people who wind up happy (and healthy) as they grow old shows that the most important part of life to cultivate is a series of stable, long-term love relationships...Here’s a handy formula to go by: Happy people love people and use things; unhappy people use people and love things."

Thursday, July 21, 2022

What Driving a New Car Teaches Us About Managing Enterprise Risk


If you have purchased a new car in the past few years, you probably have many new technological features to "assist" your driving:  forward collision warning, lane departure warnings, lane keeping assist, back-up camera, adaptive cruise control, blind spot monitoring, etc.   Hopefully, these features make us safer.  Theoretically, they should help reduce human error.  However, four countervailing forces emerge when you install such an array of safety features in a vehicle.  

1.  Drivers develop a false sense of security, and therefore, they take more risk.  Perhaps they drive faster, or they are more apt to text behind the wheel.  

2.  Drivers become overly dependent on the technology.  Over time, their skills erode as the car makes more and more decisions for them.   Consider a scenario where suddenly your back-up camera and parking assist features go away.  Can you parallel park as effectively as you did ten years ago?  

3.  Drivers develop alarm fatigue.  All the warnings and signals become annoying, and drivers simply start ignoring some of them (or turning them off).   

4.  The additional complexity of the vehicle becomes problematic and adds to the risk of a major failure.  For instance, consider renting a vehicle from a different manufacturer than the car you own.  Will the different systems befuddle you a bit? Could the confusion lead to errors?  Similarly, could the added complexity mean that the car is more prone to break down and be costly to repair, given all the technology embedded in the vehicle?

These four concerns all apply to your enterprise as well.  As you add systems to "assist" decision makers, you face these countervailing forces.  Redundant systems may provide crucial back-up to protect against human error, but they add complexity and they create these offsetting risks because of human nature.  We should all be aware of these other risks as we embrace the use of fail-safe, back-up, and decision support systems in our organizations.  

Monday, July 18, 2022

Ingredients of a Career "Hot Streak"

Director Peter Jackson
Source: Indiewire

Under what conditions do people experience a burst of unprecdented success in their careers? Scholars have been studying the ingredients of career "hot streaks" for some time. At first, scholars thought that such unusual periods of success occurred randomly. However, new research methods have capitalized on artificial intelligence to advance our understanding of such hot streaks. Scholars Lu Liu, Nima Dehmamy, Jillian Chown, C. Lee Giles, and Dashun Wang developed an AI system to study the work of 2,128 artists, 4,337 directors, and 20,040 scientists.  They found that hot streaks emerged when these artists, directors, and scientists first engaged in a period of broad exploration of creative options and then shifted to an exploitation phase in which they focused intensely in a particular domain.  Kellogg Insight summarized their findings:

The results make clear the “recipe” for a hot streak: exploration of creative options followed by exploitation of a specific “lane” of work ultimately leading to greater success. This held true across all three domains studied.  For example, director Peter Jackson made films that fell into horror, comedy, drama, and other genres (reflecting a period of exploration) before hitting it much bigger with the Lord of the Rings fantasy franchise. Analysis of painter Jackson Pollock’s work, similarly, showed exploration of a wide range of styles before the focused “drip period” (1946–1950) that elevated him to global fame.

The research found, further, that exploration or exploitation by itself is not enough for a hot streak. That is, only the specific exploration-exploitation sequence led to the highest increase in likelihood of a hot streak: hot streaks following that sequence were 20.5 percent, 13.8 percent, and 19.2 percent more likely for artists, directors, and scientists, respectively, versus after a random point in a given career. Exploration and exploitation alone were associated with no such increase.

“If you just do one or the other, you don’t get the full impact,” Chown says. “It has to be the combination of exploration followed by exploitation: experimenting in different areas, learning different domains and approaches, then really hunkering down and developing that body of high-impact work.”  Wang agrees: “Our work shows that people experiment and likely gain new skills from work in different subfields, and then help find the best one to exploit, which seem crucial for hot streak.”

As I read this study, I was reminded of a terrific book I read several years ago by David Epstein.  In that book, Range: Why Generalists Triumph in a Specialized World, Epstein argues that we should not specialize early and narrowly in our lives.  Instead, we should explore and develop competence in multiple areas.  He argues that these generalists ultimately create more innovation than people who specalize narrowly.   This AI-driven study of scientists, directors, and artists takes Epstein's argument one step further.  It confirms the value of being a generalist, though it emphasizes the benefits of a shift from broad competence to specific expertise over time.  Either way, both Epstein's book and this study provide a compelling argument for not restricting yourself too early in your career.  Unfortunately, in many professions, the pressure to specialize can be very powerful.  Take my profession, for instance.  In management academia, the path to early career success seems to emphasize mastery of a narrow domain - and too often, that entails a quite esoteric focus.  Broadening the mind has many benefits, and we should not forget that as we coach and mentor young people in their careers.  

Tuesday, July 12, 2022

Announcing the Release of Case Companion!

Over the past 8 months, I've been working on an exciting new project in collaboration with Harvard Business Publishing & Torrance Learning. We are now proud to announce the release of Case Companion - an engaging and interactive multi-media introduction to case study analysis that is ideal for undergraduates or any student new to learning with cases. 

Thank you to our amazing team including Jenna Fleming, Jordan McKenzie, John Lafkas, Carla Torgerson, Allison Mitton, Anthony Reisinger, Nicole Harris, Anne Spencer, Dave Di Iulio, and Elie Honein.  What a pleasure to work with all of you!  I hope that faculty members and students will benefit from this new multi-media experience that teaches us how to analyze a case study.  

Employee Retention: The First 90 Days

Source: Small Biz Daily


Chip Cutter of the Wall Street Journal reports today on the work being conducted at several firms to reduce new employee turnover, particularly among hourly workers.  Cutter writes:

Hold on to an employee for three months, executives and human-resources specialists say, and that person is more likely to remain employed longer-term, which they define as anywhere from a year on in today’s high-turnover environment. That has led manufacturing companies, restaurants, hotel operators and others to roll out special bonuses, stepped-up training and new programs to prevent new hires from quitting in their first three months on the job.

Cutter reports that many firms have retooled their onboarding, training, and feedback processes to focus on reducing "quick quits" - i.e., employee departures during those first ninety days.  Employers have come to understand that it takes roughly three months for new employees to build a comfortable, steady work routine.  Employers are working hard to set clear expectations, as well as to establish short-term goals for each employee.   Then, they are keeping in close touch with those employees to measure progress, listen to concerns, and provide feedback.   Firms are also providing their front-line supervisors with critical tips for how to help smooth that transition for new employees, often based on extensive research on employee retention at the companies.  The payoff is clear for these firms: employee turnover is extremely costly, particularly in this era of worker shortages.  

Of course, I'm quite sure firms need to tread carefully with these efforts.  Sometimes, a new employee is simply not a good fit.   Trying desperately to hold onto that person might, in fact, be a case of the sunk cost effect (throwing good money and effort after bad).  Determining how to let certain people walk away because they aren't likely to be engaged, satisfied, and productive team members is a key capability that firms must develop as well.